
What Is a Clarity Credit Report and Why Subprime Lenders Use It
A Clarity credit report is a specialty credit report from Clarity Services, a consumer reporting agency owned by Experian that tracks subprime and alternative lending activity. It shows things your regular credit report usually does not: payday loans, title loans, installment loans, rent-to-own accounts, and check-cashing history. Subprime lenders use it because a standard FICO report often has little or nothing for a thin-file borrower, and Clarity gives them a record of how you have handled small-dollar, high-cost credit.
If a payday or subprime auto lender pulled your credit and you never heard of Clarity, this is what they were looking at.
What Is a Clarity Credit Report?
Clarity Services is what the industry calls a specialty consumer reporting agency. It is regulated under the Fair Credit Reporting Act (FCRA) just like Equifax, Experian, and TransUnion, but it focuses on a narrower slice of the lending world.
According to the Consumer Financial Protection Bureau, Clarity collects and reports information on payday loans, installment loans, auto loans and leasing, check-cashing services, rent-to-own transactions, and other financial services aimed at lower-income and subprime consumers.
Experian acquired Clarity in 2017. Today it is the largest FCRA-regulated bureau focused on the subprime and “credit invisible” market.
Why Do Subprime Lenders Use Clarity Instead of Your Regular Credit Report?
Because your traditional credit report often does not tell them what they want to know. Roughly one in ten adults has little or no traditional credit history. A payday or title lender cannot underwrite a loan off a blank FICO file, so they turn to alternative data.
Clarity fills that gap. It shows a lender:
- Whether you have taken out payday or short-term loans before, and whether you repaid them
- How many small-dollar loans you have open right now
- Recent applications and inquiries at other subprime lenders
- Bank and payment behavior tied to alternative financial services
For a lender making a high-risk loan, that history is more useful than a credit score built on mortgages and credit cards you do not have. It also lets them see if you are stacking multiple payday loans at once, which is a red flag they watch for.
What Information Shows Up on a Clarity Report?
A Clarity report pulls from lenders and services most mainstream bureaus ignore, including:
- Online and storefront payday and single-payment lenders
- Installment lenders
- Auto title and rent-to-own companies
- Check-cashing outlets and some prepaid card activity
- Applications and inquiries you made at any of the above
It can also include identity and address information, along with a proprietary risk score.
Is a Clarity Score the Same as a FICO Score?
No. The Clarity score is its own model built to predict risk for subprime lending. It is not a FICO score or a VantageScore, and the number will not match what you see on a typical credit app.
A lender that only checks your FICO score may never look at Clarity at all, and a lender that uses Clarity may weigh it heavily. That is why two lenders can reach very different decisions on the same applicant.
How to Get Your Free Clarity Report
Because Clarity is FCRA-regulated, you have the right to see what it holds on you. You can:
- Request one free report every 12 months
- Request your Clarity risk score
- Place a free security freeze on your Clarity file
You can start at clarityservices.com or call 866-390-3118. Checking your own report is a soft pull and does not hurt any score. If you use payday, title, or installment loans, it is worth pulling this report at least once so you know what subprime lenders are seeing.
Can You Dispute Errors on a Clarity Report?
Yes, and this is where it matters most. Clarity has the same duties as any other credit bureau under the FCRA. If your Clarity report shows a loan that is not yours, a wrong balance, an account you already paid off, or activity from identity theft, you can dispute it.
Under 15 U.S.C. § 1681i, the bureau generally must investigate a dispute, usually within 30 days, and correct or delete information it cannot verify. The lender that supplied the wrong information also has a duty to investigate and fix it. If your report contains fraudulent accounts from identity theft, you can use the stronger identity theft block process to force removal.
Errors on a specialty report can quietly cost you. A wrong payday loan or a fraudulent title loan on your Clarity file can get you denied or pushed into worse terms without you ever knowing why. When a bureau or lender ignores a valid dispute, that can be an FCRA violation. Our Mississippi consumer protection lawyers handle exactly these cases.
Frequently Asked Questions
Is Clarity a real credit bureau?
Yes. Clarity Services is an FCRA-regulated consumer reporting agency owned by Experian. It focuses on subprime and alternative lending data rather than traditional credit accounts.
Does checking my Clarity report hurt my credit?
No. Requesting your own report is a soft inquiry and does not affect any credit score. You are entitled to one free Clarity report every 12 months.
Why does a payday lender check Clarity?
Because your standard credit report may not show prior payday, title, or installment loans. Clarity gives subprime lenders a record of that activity and flags if you have several small-dollar loans open at once.
Can identity theft show up on a Clarity report?
Yes. Thieves often target payday and installment lenders. If a loan on your Clarity file is not yours, you can dispute it and request that the fraudulent information be blocked.
What if Clarity refuses to fix an error?
A bureau that fails to properly investigate a valid dispute may be violating the FCRA. At that point, an attorney can push for correction and pursue damages.
Check What Subprime Lenders See About You
Most people never think about Clarity until a loan gets denied or a debt they do not recognize turns up. If you have used payday, title, or installment lenders, pull your free Clarity report and read it closely. If you find a loan that is not yours, a wrong balance, or fraud, dispute it in writing and keep records.
If Clarity or the lender will not correct a real error, contact Ware Law Firm to review your report and your rights under the FCRA.
Author Bio
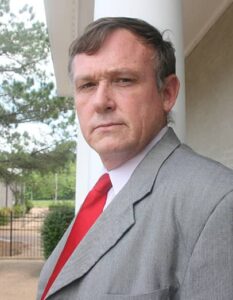
Daniel Ware is CEO and Managing Partner of Ware Law Firm, a consumer protection law firm in Magee, MS. With more than 25 years of experience practicing law, he has zealously represented clients in a wide range of legal matters, including identity theft, lemon law, debt collection, and other consumer protection matters.
Daniel received his Juris Doctor from the University of Mississippi School of Law and is a member of the Mississippi Trial Lawyers Association. He has received numerous accolades for his work, including being named among The National Top 100 Trial Lawyers.